SATELLITE MANUFACTURING INNOVATION
Small GEOs Making Their Way in the Industry:
Combining Flexibility and Scalability amid Strong Market Uncertainty
Maxime Puteaux, Principal, Novaspace
Gabriel Deville, Senior Consultant, Novaspace
Small GEO platforms (<2 tons) are seeing rising demand due to their agility, cost-effectiveness, and suitability for emerging applications such as regional broadband and gap-filling for emerging or established governments. This trend highlights the growing preference for more frugal investments through smaller and more versatile platforms as an alternative to traditional large GEO satellites and high-throughput NGSO constellations. However, to date, the supply of such small systems has been slow to materialize.
A new option in a multifaceted connectivity landscape
The geostationary communications satellite industry has been shaped since the 1970s by government needs in traditional space powers, and by the rise of private communications satellite operators in the 1980s. In the 1990s, the advent of digital satellite broadcasting created a vast television broadcast market for commercial satellite operators, driving the expansion of paid television services.
Growing bandwidth needs (and longer satellite lifetimes) pushed operators toward ever larger and more powerful satellites, reaching up to 6.5 tons at launch (all-electric) and 25 kW of power. The introduction of HTS design in the 2000s (multi-spot beams with frequency reuse) enabled operators to shift focus from broadcasting to broadband connectivity.
Now, alongside opportunities in both civil and defense sectors worldwide, major government actors in satellite communications are showing increasing interest in small GEO solutions. One one hand, they are a lower investment commitment and in theory faster to manufacture and roll-out. On the other, they allow to cover smaller needs, fill gaps or provide redundancy through a smaller investment. This is of particular interest for emerging governments or large governments or commercial GEO operators with capability weak spots.
Small GEOs face indirect competition from traditional large satcom manufacturers
Traditional manufacturers of large communications satellites (3–6.5 tons at launch, 5–25 kW power) offer products at far higher costs than small platforms, while being more cost-efficient for multi-mission payloads. The market is dominated by three legacy players, namely Airbus D&S (ADS), Thales Alenia Space (TAS), and Boeing.
Facing the decline of broadcasting and uncertainty around demand for uses like military communications and mobile connectivity, these large integrators now proposed software-defined radio (SDR) satellites for higher flexibility (allowing to follow a more dynamic and fluctuating, data-centric demand on Earth). While the flexibility argument for SDRs has won over some operators (40 commercial SDR orders to date, of which 71% for ADS/TAS and the rest to Astranis), their high cost ($250M per satellite) and development delays disqualify SDRs for operators that fail to meet their capital requirements.
As none of the legacy players offer competitive products for the small GEO market, new entrants have emerged.
So far, only Astranis has deployed small GEOs, with a 500-kg satellite of limited capacity (8 Gbps, 8 years), offered under a leasing model where Astranis operates the satellite for its customers. Swissto12 is marketing its small GEO HummingSat platform, with five units already ordered by major operators (Intelsat – 1, Inmarsat – 3, and Astrum Mobile in Singapore – 1). Other companies are eyeing the segment by leveraging their LEO experience (e.g., Terran Orbital aims to expand into GEO with its MicroGEO concept, potentially for the U.S. DoD).
Against VHTS and NGSO high CAPEX, small GEO wins with incremental logic
Hence, small GEOs are progressing in the commercial GEO order book. New manufacturers such as Astranis, Swissto12, and ReOrbit have captured 40% of all non-military GEO satcom orders since 2021.
The move toward smaller, cheaper GEO satellites is largely driven by market uncertainty from the massive capacity increase provided by NGSO megaconstellations and GEO-VHTS systems.
The significant investments required for these large-scale systems are often unsuitable for mid-sized or regional operators, whose fleets and revenues are modest. These operators struggle to justify new investments given the risks of monetizing huge capacity in an increasingly competitive landscape.
This trend for small GEOs also drives demand for software-defined or flexible payloads, now integrated into platforms by Astranis and ReOrbit. The military sector is likewise expected to sustain demand for small GEOs, since their lower costs, high agility, faster production timelines, and advanced capabilities enhance resilience through proliferation and supplier diversification—contrasting with mega-programs of astronomical cost (e.g., WGS in the US).
Operators of all types are eyeing small GEOs
Both civilian and military players, traditionally focused on “classic” GEO systems, are now considering small GEOs to meet sovereign needs.
For example, the U.S. Space Force (USSF) signaled interest in 2023 by issuing a request for information on small GEOs. This move underscores their intent to leverage them for military communications, either via commercial service agreements or government-owned dedicated constellations.
In September 2024, the USSF announced plans to launch a “maneuverable GEO” program as early as 2025, strengthening collaboration with commercial GEO operators. After a period focused on NGSO systems (the SDA’s Proliferated Warfighter Space Architecture), this new program shows GEOs are far from abandoned—multi-orbit complementary fleets are drawing growing interest.
Other governments are expected to follow suit. In Europe, the replacement of existing systems between 2022–2026 is expected to drive new GEO satcom demand. While a European multi-orbit constellation project (IRIS²) exists, funding uncertainties and the push for strategic autonomy are prompting nations like France, the UK, and Italy to examine small GEOs as a viable modernization path. Others, such as Greece (MoD RFI in July 2024), are likely to adopt a first sovereign defense communications satellite.
Benchmark of small GEO satellite solutions with alternatives

Temporary anomaly or structural shift? GEO comsats have been slimming for 5 years
Launch mass for GEO satcoms historically kept increasing, reflecting bandwidth and lifetime needs, availability of heavy launchers, and dominance of chemical propulsion.
But over the past decade, GEO satcom demand has undergone a radical shift. Orders for large satellites have dropped sharply, due to combined technological, economic, and competitive pressures.
Advances in satellite tech have halted mass growth: smaller GEO platforms can now perform tasks once reserved for large satellites, offering similar capabilities at lower cost. The rise of HTS, electric propulsion, and flexible payloads has reinforced this trend, enabling smaller GEOs to effectively serve targeted markets with shorter delivery times.
Annual avg. launch mass and satellite count trends for all GEO satellites, from 2015-2027

New needs for space transportation
Unlike traditional large GEOs injected into GTO or placed directly in GEO by heavy launchers, small GEOs now prefer more flexible and cost-efficient deployment solutions. This shift fuels demand for shared GTO rides and for orbital transfer vehicles (OTVs) capable of final GTO-to-GEO delivery.
OTVs could thus become a key link to optimize launcher use, provide more tailored deployment services, and better fit market needs—provided they are more time- and cost-efficient than traditional solutions.
For launch operators, this creates a new mid-market segment between standard LEO missions and direct GEO launches, redefining rideshare strategies and opportunities to geostationary orbit.
About Novaspace’s satellite market intelligence and executive summits
Novaspace is the leading global consulting firm specializing in the space sector, boasting 41 years of experience and data collection. Its market intelligence suite covers all space markets, leveraging extensive databases used by space agencies and industry players over the world, and one of the most extensive stakeholder reaches.
In the latest version of its Satellites to be Built and Launched report (28th Edition), it delves into all satellite manufacturing and launch markets.

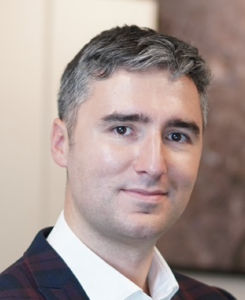
Maxime Puteaux is a Principal at Novaspace and manager of its Space Infrastructure team, specializing in upstream space markets. He has managed over 100 consulting assignments for customers across the world. In addition, Mr. Puteaux has regularly provided commentary about space sector trends and developments to various media outlets.

Gabriel Deville is a Senior Consultant at Novaspace’s Space Infrastructure center of expertise, where he oversees consulting assignments and market intelligence reports for government and commercial clients. He is the Editor of Novaspace’s flagship report Satellites to be Built and Launched.

Unlocking Rapid, Reliable National Access to Space
Nicolò Donà dalle Rose, Business and Corporate Development Director, Loft Orbital
In an era defined by persistent geopolitical uncertainty, the imperative for nations to secure their strategic interests has never been more pronounced. From evolving security threats to the need for advanced environmental monitoring, the ability to control space infrastructure underpins national security, economic development, and the need to maintain global competitiveness. National leaders need simple, reliable, and transparent solutions to ensure continuous access to space.
Growing Demand for Sovereign Space Capabilities
Around the world, demand for space-based capabilities is accelerating. Emerging economies once dependent on foreign providers are now seeking to establish domestic programs. And established spacefaring nations are looking to expand their capabilities to meet new challenges and maintain their competitive edge.
The use cases are increasingly complex, spanning defense and civilian applications alike:
- National Security: intelligence, surveillance, reconnaissance, secure communications, and early missile warning systems.
- Environmental & Disaster Monitoring: disaster response and pro-active mitigation planning, wildfire and bushfire management, deforestation, and weather monitoring
- Precision Agriculture & Food Security: crop health monitoring, water resource management, monitoring productivity and crop yields
- Energy & Infrastructure: tracking illegal mining activity, monitoring existing energy resources and identifying new sources, identifying damage of critical infrastructure
- Connectivity & Navigation: broadband access for remote regions, direct-to-device networks, and precise positioning for infrastructure and autonomous systems.
Each nation’s objectives are unique, but they share a common challenge: how to deploy capabilities quickly, reliably, and affordably—while maintaining independent ownership of these systems.
Legacy Barriers to National Space Programs
But the path to achieving these goals has historically been fraught with challenges. Traditional aerospace companies have lengthy development cycles and a lack of transparency regarding the underlying technology and operational control. By the time systems are launched, the technology may already be obsolete and no longer able to meet emerging threats and opportunities.
The legacy approach to space infrastructure development has also proved to be complex and prohibitively expensive. National leaders, seeking to quickly acquire critical and reliable capabilities, have at times been forced to accept these limitations, only to find themselves heavily invested in systems that were difficult to adapt, costly to maintain, and lacked the agility to respond to rapidly changing requirements.
Recognizing these challenges, a new generation of providers seeking to capture market share have begun promising risky solutions – from unrealistic timelines to infeasible technological capabilities – based on minimal space heritage. Nations, particularly those new to the space arena, have often felt burned by experiences where they were offered opaque, “black box” solutions.
The result: governments are forced into a false choice between slow, inflexible legacy providers and risky, unproven newcomers.
A New Approach for Simple Access to Space
The future of national space programs demands a new paradigm—fast, simple, and reliable access to orbit that balances sovereignty with proven commercial expertise. Loft Orbital (Loft) offers a unique “Space Infrastructure as a Service” model where nations can take advantage of existing engineering and operational expertise, close industry relationships, and established on-orbit sensor and on-orbit AI capabilities to enter this new paradigm.
Loft is building joint ventures around the world to help nations take advantage of this framework to solve their unique mission needs. In tandem with Marlan Space, Loft has created Orbitworks to build domestic satellite integration capabilities within the United Arab Emirates. Organizations there will have access to a novel AI-powered satellite constellation flying multiple types of Earth observation sensors with advanced edge computing. With partnerships like Orbitworks, Loft is helping nations take advantage of this paradigm to solve their unique mission needs.
1. Speed to Orbit
Loft drastically reduces time from concept to orbit.
By maintaining satellites in inventory and streamlining integration with a turnkey satellite platform, nations can deploy capabilities in months instead of years—ensuring assets are operational before threats or opportunities emerge. Loft has spent years developing an agnostic bus interface – the Hub – so that customers don’t have to. This approach eliminates the need for nations to invest in costly and time-consuming satellite development, allowing them to focus on their specific mission requirements. Loft provides the expertise and infrastructure, while empowering nations to retain control over their assets.

Multiple satellite buses await integration at Loft’s I&T facility in Golden, Colorado. (Photo: Loft Orbital)
2. Simplicity and Flexibility
Simplicity translates to user-friendly interfaces and modular architectures that de-mystify satellite operations and reduce the burden of technical expertise. Organizations can leverage AI-driven applications that maximize utility of the satellites while customizing the operations to national needs. This model can also be flexibly deployed out of the United States, France, and the United Arab Emirates.
Further, Loft’s business model ensures that its international partners are actually being delivered a service, with measurable performance metrics. Loft’s end-to-end model, from satellite production to deployment and operation, simplifies programs and allows its partners to rely on a dependable, continuous partner.

Loft’s full concept of operations enables customers to quickly and reliably receive critical information to solve their unique challenges.
3. Proven Reliability
Loft combines commercial agility with spaceflight heritage. Every mission is backed by flight-proven technology, rigorous testing, and a record of operational performance. Nations retain full control over their assets, avoiding reliance on opaque or untested systems. This ensures that space programs are not just acquired, but truly owned and operated by the nations themselves. But Loft doesn’t just set up the capabilities and walk away. We offer continued operational support to make sure nations are able to meet their key mission objections, thereby enhancing sovereignty and long-term strategic resilience.
Reliability also translates to Loft’s unique business model. The moment a customer partners with Loft, they have immediately de-risked most of the hardware and processes needed for the mission, as it is available and proven. As a result, funding is immediately translated into capability.

The Orbitworks AI&T facility in Dubai, UAE is capable of integrating multiple satellites and a variety of payloads. (Photo: Loft Orbital)
With the ability to support domestic and export partnership opportunities, establish local production and satellite AIT facilities, and license key elements of a proprietary tech stack, Loft is enabling nations to unlock the full potential of space infrastructure.
Organizations can take advantage of this rapid, reliable, and cost-effective path to orbit to leverage the full power of satellite technology for their security, prosperity, and strategic autonomy in a rapidly changing world.

Loft maintains a large inventory of small satellites ready for test and integration as soon as the payload is delivered. The satellites can be made launch-ready in as little as 6 months from payload delivery. (Photo: Loft Orbital)

Nicolò Donà dalle Rose is Loft’s Director of Business and Corporate Development. At Loft, he leads the Strategic Initiatives team, which focuses on global partnerships, business development, and international efforts. Further, he leads all efforts in Asia-Pacific for the company. He also serves as a leader at Orbitworks, Loft’s Joint Venture with Marlan Space, focused on developing sovereign space capabilities. Prior to Loft, Nicolò has served in leadership roles at Vantor (formerly Maxar Technologies), a leading Earth observation satellite operator, and Avascent, a space-focused consultancy now under Oliver Wyman. Nicoló has a degree in International Politics from Georgetown University in Washington, D.C., and he is based in New York City.
Industrializing Space: How Does Satellite Manufacturing Actually Scale?
Tina Ghataore, Group Chief Strategy and Revenue Officer & CEO, North America, Aerospacelab
When I first entered this industry, success was defined by delivering a single spacecraft. That milestone once symbolized mastery. Today, the challenge looks very different. It’s no longer about proving you can build and operate a single satellite, it’s about whether you can deliver dozens, even hundreds, on time, at cost, and with reliability proven in orbit. The question is no longer “Can you build one?” but “How many can you deliver and how quickly without compromising quality?”
This transformation isn’t just technical. It’s industrial. Mass manufacturing in space is no longer a slogan — it’s a discipline. It demands rethinking how we design and assemble spacecraft to prioritize throughput.
Why Scale — and Why Now?
Several forces are converging to make scalability essential. Every sector, from energy to logistics, defense to telecom, now depends on real-time data. According to Satellite Today, satellite data consumption is growing by nearly 30 percent every year. That pace doesn’t wait for one-off missions or bespoke spacecraft. It demands hundreds of satellites working in unison, a production speed and capability that mirrors the pace of the digital economy. If you ask me, the math is quite simple here: economics has finally caught up with ambition.
With its reusable Falcon 9, SpaceX has transformed the cost of access to orbit, slashing launch prices to roughly $2,500 to $4,000 per kilogram — a fraction of what it was a decade ago. Each reused booster reinforces a simple truth: routine access to space is now real. And with Starship on the horizon, aiming for launch costs near $1 million per flight, the real bottleneck is no longer lift-off, it’s now effective delivery of industrially manufactured spacecrafts.
The old GEO versus LEO debate is essentially over. The future is multi-orbit. LEO constellations provide low latency, resilience, and security; MEO and GEO add persistence and coverage. LEO satellites’ shorter five- to seven-year lifespans create a natural cadence of continuous replenishment, embedding innovation into each new generation. Flight data informs design improvements, manufacturing evolves, and technology scales in real time. Production is no longer a series of isolated projects; it’s a perpetual industrial flow.
At the same time, the satellite and telecom worlds are converging. Direct-to-Device connectivity is extending coverage straight to smartphones and IoT devices, turning satellites into mainstream infrastructure. Hybrid networks, shared spectrum, and seamless roaming raise expectations: satellites must now be manufactured with the same precision, reliability, and efficiency as global tech supply chains.
Geopolitics is another driver. Governments around the world are building sovereign constellations to secure autonomy, resilience, and control over critical communications and data. Space has become a strategic infrastructure. And that’s where the good stuff takes shape. These programs bring steady, long-term demand, requiring reliability, supply chain security, and transparency. Vertical integration, standardized platforms, and disciplined production are now prerequisites for national trust.

© Aerospacelab’s Cleanroom (Assembly, Testing & Integration)
From Bespoke Builds to Scaled Production
When I first joined the aerospace world, traditional aerospace thrived on the unique. Every program was tailor-made, often stretched over years, optimized for technical novelty rather than repeatability. That model no longer serves today’s demand. Constellations for telecommunications, Earth observation, connectivity, defense, and now large-scale telecom require platforms that are reproducible and configurable, not endlessly customized.
The shift is not simply about building faster. It is about moving from workshops to factories, from engineering labs to industrial systems. Scaling is about control. Hardware, software, and systems are deeply intertwined, and supplier dependencies can slow down delivery or weaken accountability. Vertical integration, understood as design, build, and qualification under one roof, is the road to secure pace and consistency. It shortens loops between design and production and keeps delivery predictable. In a constellation program, predictability is as critical as performance.

© Aerospacelab’s Cleanroom (Assembly, Testing & Integration)
Factories That Flow, Platforms That Adapt
From my experience, industrial-scale manufacturing requires facilities designed for movement, not storage. Today, satellites are purposely built to progress through stations, cleanrooms, integration areas, and testing chambers in a continuous line. Qualification is embedded, not an afterthought. Environmental tests, vibration stands, and thermal vacuums are part of the rhythm. The line does not stop; it flows.
Volume alone is not enough. I have seen firsthand how customization can slow everything down. The answer is configurability: modular platforms with standardized cores and adaptable payload interfaces. Qualify the base once, configure it many times. This approach balances flexibility with repeatability, delivering tangible benefits like faster schedules, lower unit costs, and reduced program risk.
What matters even more, is the ability to cover a wide range of volumes. Industrial lines must handle both high-volume telecom constellations and lower-volume specialized spacecraft. Customers want to know that a manufacturer can scale up or down without losing efficiency or quality. True industrial maturity comes from that adaptability. Scaling reliability means testing in parallel, collecting data continuously, and feeding improvements back into design. When done right, mass manufacturing scales quality up, not down.

© Aerospacelab’s Megafactory in Belgium – Ready for operations in 2026 with 500 satellites/year production capabilities
Proof, Resilience, Responsibility
Every spacecraft we launch and operate is proof that the industrial system works. Build, qualify, deliver, deploy—that sequence is the only metric that counts. However, industrial production can be fragile without resilience as global supply chains are subjected to pressure from component shortages, logistics delays, and geopolitical uncertainty. Keeping constellations on track means having multi-source strategies, long-term supplier partnerships, and internal production for critical parts. Inventory management is no longer just about efficiency; it is about protecting the program from disruption.
Scaling also comes with responsibility. Safe deorbiting, collision avoidance, and regulatory compliance need to be built into the process from the start.

© Aerospacelab’s Cleanroom (Assembly, Testing & Integration) with Founder & CEO, Benoît Deper and three RFS satellites ready for deployment
What’s the new baseline, now?
The numbers speak for themselves: on one side, SpaceNews projects that more than 18,000 satellites will launch this decade, which equals triple the total of what was deployed in the previous ten years and on the production front, Satellite Today forecasts the global satellite manufacturing market will exceed $57 billion by 2030, fueled by LEO constellations, their shorter lifecycles and associated steady cadence of replenishment.
With each generation, replenishment will become an opportunity to integrate new technology, feeding a continuous loop between orbit and factory. Flight data informs design improvements, manufacturing evolves, and innovation becomes embedded in the production line itself. The industry is learning and scaling in real time. Yet, although we may not yet have a Henry Ford-style assembly line for satellites, it undoubtedly seems like this era is clearly on the horizon.
In the end, the leaders of this new chapter won’t be the ones making the loudest promises but rather the ones who quietly and consistently deliver, moving from concept to constellation with speed, reliability, and proof. That, to me, is the new baseline for the industrialization of space.

Tina Ghataore joined Aerospacelab in August 2023 as Group Chief Strategy and Revenue Officer and CEO of its North American branch. She previously served as Chief Commercial Officer of Mynaric and President of Mynaric USA, positioning the company as a leading laser communications provider. Recognized as Via Satellite’s “Satellite Executive of the Year” in 2022, Tina has held senior roles at Yahsat, Panasonic Avionics, and Boeing, contributing to pioneering satellite communications programs. She holds a Bachelor of Honors in Aerospace Engineering from Kingston University and is a graduate of the International Space University.

Interview with Emile de Rijk, CEO & Co-founder, SWISSto12

Emile de Rijk is the CEO and co-founder of SWISSto12. Emile founded SWISSto12 in 2011 as a spinoff from his PhD at EPFL. He led the company’s growth into aerospace and telecommunications, making it the first scale-up to sell a geostationary telecom satellite, HummingSat, to global operators. He holds a PhD from EPFL and a Master’s in Physics from the University of Amsterdam.
The geostationary market is evolving rapidly. What industry dynamics are driving the push toward smaller and more agile GEO satellites?
Operators worldwide are facing new commercial realities that include both challenges and opportunities: a shift from broadcast to broadband business models, pressure from lower orbit constellation in certain market verticals like B2B, shorter-term visibility on future revenues, but an overall increase in demand for capacity, as well as a surge in demand for sovereign secure connectivity solutions from governments. Traditionally, geostationary satellites have been optimized for exquisite functionalities, but at the expense of being large, expensive, and slow to build. That model no longer matches all of the business cases operators face, especially in markets where a rapid response to a targeted business opportunity is needed against an affordable CAPEX expenditure.
Recent advances, such as satellite miniaturization, rideshare launch models, additive manufacturing, and digital payloads, have made it possible to design geostationary satellites that are much smaller, lighter and lower cost, yet still capable of supporting broadband, broadcast, or direct-to-device services.
Small geostationary satellites such as HummingSat complement traditional GEO assets and address emerging use cases that were previously not feasible from a unit economics perspective.
How are these market dynamics shaping the business case for GEO satellites and the way operators approach procurement today?
The unit economics of GEO satellites remain very competitive relative to other solutions, but only if targeted at specific business cases where GEO can focus on its strengths and differentiators. This moves the conversation toward smaller, more focused satellites that can meet specific market demand in a more agile fashion and at a fraction of the cost per orbital position.
The key for GEO operators is specialization, which means focusing on secure communications, regional broadband, broadcast replacements, and targeted satellite to device applications from GEO or gap-filling missions that play to GEO’s strengths.
Additive manufacturing is now fully industrialized in RF and payload systems. How is it changing the economics and performance of satellite manufacturing?
The industrialization of 3D printing for RF and payload systems has been a significant technological leap in developing space hardware, which we have pioneered at SWISSto12. By replacing complex payload product assemblies with integrated, 3D-printed products and further advanced designs, manufacturers can dramatically reduce part counts, weight, and production time while improving mechanical, thermal, and functional radiofrequency performance.
The impact extends well beyond cost and efficiency. Additive manufacturing allows engineers to design product functionalities that were previously impossible to achieve using traditional methods and that unlock new levels of performance, compactness and robustness – especially important in business cases such as connectivity, where every bit of capacity counts. Additive manufacturing also supports greater design flexibility, enabling rapid iteration and customization for specific mission requirements.
The additive manufacturing revolution for RF space systems has created compounding benefits, leading to lower weight, more compact payloads that can be delivered on much smaller satellite platforms than was possible before. This has allowed us at SWISSto12 to create a new class of geostationary SmallSats with HummingSat that contributes to re-igniting the GEO market.
As governments emphasize sovereignty and resilience in space, how are satellite innovations enabling independent capability without the cost of a traditional space program?
Advances in smaller and more cost-efficient geostationary satellites are helping enable satellite sovereignty for smaller nation states that have historically been priced out of dedicated and secure GEO connectivity due to the high costs and large satellites previously associated with such space programs.
Many countries that lack the resources to design, launch, and operate their own satellites have traditionally relied on leasing capacity, or shared multinational assets, or large LEO constellations. While these arrangements provide access to critical connectivity, they often come with trade-offs in sovereignty, such as limited control over infrastructure, reliance on third parties, and exposure to the strategic interests of other partner nations, commercial operators, and technology vendors.
The market entry of GEO SmallSats, which are more affordable to procure and operate, allows many countries to independently own and operate sovereign space assets for the first time. In a world increasingly in flux, the security such sovereign satellite capability offers is a compelling opportunity for many nation states.
Why is Satellite-to-Device service a compelling option for the Asia-Pacific region?
Satellite-to-device, or direct-to-device connectivity, has particular resonance in the Asia-Pacific region due to its geography, diversity, and growth in demand that often exceeds the capacity ground networks can offer. APAC has a diverse terrain, mixing dense urban areas and rural communities spread across areas where terrestrial infrastructure is either difficult or uneconomic to deploy.
Being able to connect directly to standard smartphones or low-cost terminals without additional ground infrastructure changes the equation for coverage, resilience and offloading of terrestrial networks in certain application cases. Satellite-to-device services complement terrestrial networks rather than replacing them, helping to fill gaps, support low coverage areas, enable efficient broadcasting to offload ground networks from unnecessary capacity demand surges, facilitate disaster recovery, and ensure continuity when other systems are down.
Asia-Pacific is a fragmented region with diverse needs. How can satellite operators adapt to serve such diverse requirements?
APAC has a wide range of connectivity needs – from government sovereign communications to delivering broadband to remote rural areas, continuing broadcast services while tackling often challenging weather conditions that sometimes affect satellite link budgets.
Natural disasters such as typhoons, earthquakes, and floods can disrupt ground networks, making satellite communications critical to disaster response and continuity of operations. In addition, the sheer geographic scale — spanning from South Asia to the Pacific Islands — means no single architecture can serve all requirements effectively.
To address these opportunities, the industry is seeing greater interest in more agile and cost-efficient geostationary platforms that can bring affordable focus on specific business cases or regions. These satellites can be tailored to specific coverage areas or mission needs, offering a practical alternative solution to traditional large GEO assets and proliferated LEO systems. This approach is opening new pathways to affordable, sovereign connectivity across the region.
What excites you most about the Asia-Pacific region today?
What’s exciting about Asia-Pacific is the speed of transformation and diversity of business cases and requirements. The region is increasingly at the forefront of innovation in the industry, as governments prioritize space capability as part of national resilience strategies, while commercial operators are experimenting with hybrid networks and next-generation payloads.
In many ways, the Asia-Pacific is emerging as an innovative proving ground for the next era of more agile satellite communications.